All Categories
Featured

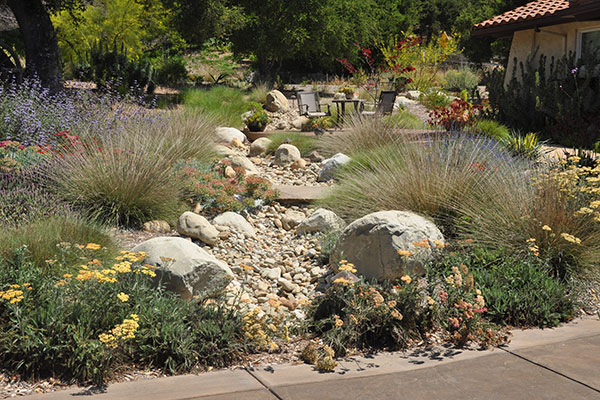
Optimizing CRE Landscaping for 2026 ESG Benchmarks
Table of Contents
According to the IFRS Foundation's June 2025 jurisdictional profile, Phase I obligatory reporting started for specific noted business from annual periods starting on or after 1 July 2025, Stage II begins on or after 1 July 2026 for another associate of listed business, and Stage III begins on or after 1 July 2027 for all staying listed business and SECP-licensed non-listed public-interest business.
Landscape MaintenanceThey are live compliance milestones. A 2nd ISSB-related advancement is similarly essential: the standards are currently being tuned for implementation, not merely promoted. In December 2025, the ISSB released targeted amendments to the greenhouse gas emissions disclosure requirements in IFRS S2 in reaction to application obstacles identified as business began using the standard.
Landscape MaintenanceThe marketplace is moving from principle-setting to execution detail. Business ought to anticipate more analysis on how emissions are determined, boundaries are specified, and information is managed. A common error in conference rooms is to check out the EU's 2025 Omnibus package as a retreat from sustainability reporting. It is much better comprehended as a recalibration.
It likewise estimated that proposed CSRD scope changes and future ESRS modifications might decrease administrative expenses by about 4.4 billion each year. That is genuine simplification, however it is not deregulation in the broad sense many executives wished for. The tactical message is this: Europe is attempting to lower reporting burden, not remove reporting expectations.
Readying Commercial Facilities for 2026 ESG Benchmarks
That means materiality judgments, consistency, and presentation quality will still matter in 2026 and beyond. Businesses exposed to the EU should get ready for a reporting environment that is rather lighter administratively, however not looser in supervisory expectation. For smaller companies and value-chain press reporters, the essential EU development is the voluntary SME standard.
That is a signal worth reading carefully. Even where reporting is formally voluntary, value-chain pressure is making structured disclosure significantly unavoidable. The next wave of ESG reporting will be shaped as much by format as by material. EFRAG's VSME digital template and XBRL taxonomy are intended to make it possible for digital sustainability reporting for non-listed SMEs, with updated materials launched through late 2025 and February 2026.
That may sound technical, however the company significance is straightforward: regulators, loan providers, consumers, and software vendors increasingly want sustainability data in machine-readable kind, not just polished PDF narrative. This matters well beyond SMEs. When reporting ends up being digital, inconsistencies appear quicker, benchmarking ends up being simpler, and guarantee gets sharper. Companies that still handle ESG reporting in fragmented spreadsheets and manual narrative workflows will find 2026 to 2027 unpleasant.
A significant trend for 2026 and 2027 is that sustainability assurance is ending up being institutionalised. The IAASB's ISSA 5000 sets a global baseline for sustainability guarantee and is efficient from 15 December 2026, with early adoption motivated. In parallel, IESBA's sustainability ethics and self-reliance standards likewise become efficient in December 2026, apart from certain value-chain independence arrangements that come later.
Business should stop dealing with guarantee as an end-stage external review and start treating it as a design requirement. By 2027, weak proof trails and vague narrative claims will be far more exposed than they were in the very first generation of ESG reporting.
Comparing Legacy Versus ESG Maintenance Standards
TNFD's 2025 Status Report identified more than 500 first- and second-generation nature-related reports and stated 620 organisations from over 50 nations or areas had actually publicly dedicated to begin TNFD-aligned reporting for fiscal years 2024, 2025, or 2026. TNFD is likewise continuing to deepen sector assistance, with draft innovation and communications guidance open for assessment and final sector guidance expected by June 2026. For organizations, the essential takeaway is not that every business requires a different nature report tomorrow.
Sectors with supply-chain direct exposure, land-use intensity, water reliance, extractives, food systems, infrastructure, or pharmaceuticals should assume that nature-related metrics and story will end up being more material in 2026 and 2027. GRI remains extremely appropriate, especially for stakeholder-oriented and impact-focused reporting. Its revised Climate Change and Energy Standards, GRI 102 and GRI 103, were published in June 2025 and work for reporting from January 2027.
That means companies utilizing GRI, particularly those with high-impact sectors or broad stakeholder expectations, ought to not assume their existing disclosures will remain adequate. The more comprehensive lesson is that the market is separating into two connected however unique reporting questions: what matters to business worth, and what matters to individuals and world effects.
The rules use to big companies doing business in the state, with limits depending on the statute. The practical repercussion is that even where federal ESG politics remain contested, large companies can not presume hold-up everywhere. They require a jurisdiction-by-jurisdiction readiness plan. For numerous multinationals, 2026 will be the year when state-level disclosure responsibilities, EU requirements, and ISSB-based financier expectations begin clashing inside one reporting calendar.
Optimizing Commercial Landscaping for 2026 ESG Benchmarks
Develop one core reporting architecture anchored in ISSB ideas, then map outside to ESRS, GRI, California, and sector-specific requirements. Treat guarantee readiness as a 2026 build concern, not a 2027 clean-up exercise. Digitise sustainability information collection, controls, and tagging early, specifically where SME or value-chain information will be pulled upstream.
Translate regulatory due dates into board-level decisions now, because reporting calendars for 2026 and 2027 are already being set by regulators, not by internal convenience. The real trend, then, is not just more structures. It is a more fully grown disclosure market. ESG reporting in 2026 and 2027 will be more converged at the top, more demanding in execution, more auditable, and less forgiving of weak data.
Those that wait will find that the reporting difficulty is no longer composing the narrative. It is constructing the system behind it.
Last upgraded: April 8, 2026ESG statistics and sustainability metrics are forming how enterprises operate, report, and manage corporate sustainability. As disclosure requirements broaden across structures such as CSRD and IFRS S2, companies are under increasing pressure to produce dependable, audit-ready information across finance, operations, and supply chains. This guide combines the key sustainability stats for 2026, covering business adoption, reporting obstacles, carbon accounting, and the growing expectations from investors and regulators.
Ways to Meet 2026 ESG Benchmarks
76% of executives say sustainability is central to company strategyOnly 1 in 5 financing teams presently report on their company's ESG metrics47% of financiers cite ESG data coverage gaps as their biggest challenge41% report data quality problems, and 40% emphasize inconsistencies across vendors84% of S&P 500 companies now recognize climate modification as a monetary risk, a considerable boost from 67% in 202196% of G250 companies report on sustainability (unchanged given that 2022)85% of financiers say greenwashing claims have become a more severe problem than they were five years ago58% of investors are making regulation-aligned ESG information a priority57% of organizations say customer and financier expectations are the main chauffeur of ESG strategyScope 3 emissions account for approximately 7090% of total corporate emissionsGlobal ESG possessions under management are projected to reach $40 trillion by 2030 Sustainability is now embedded in core business decision-making.

Latest Posts
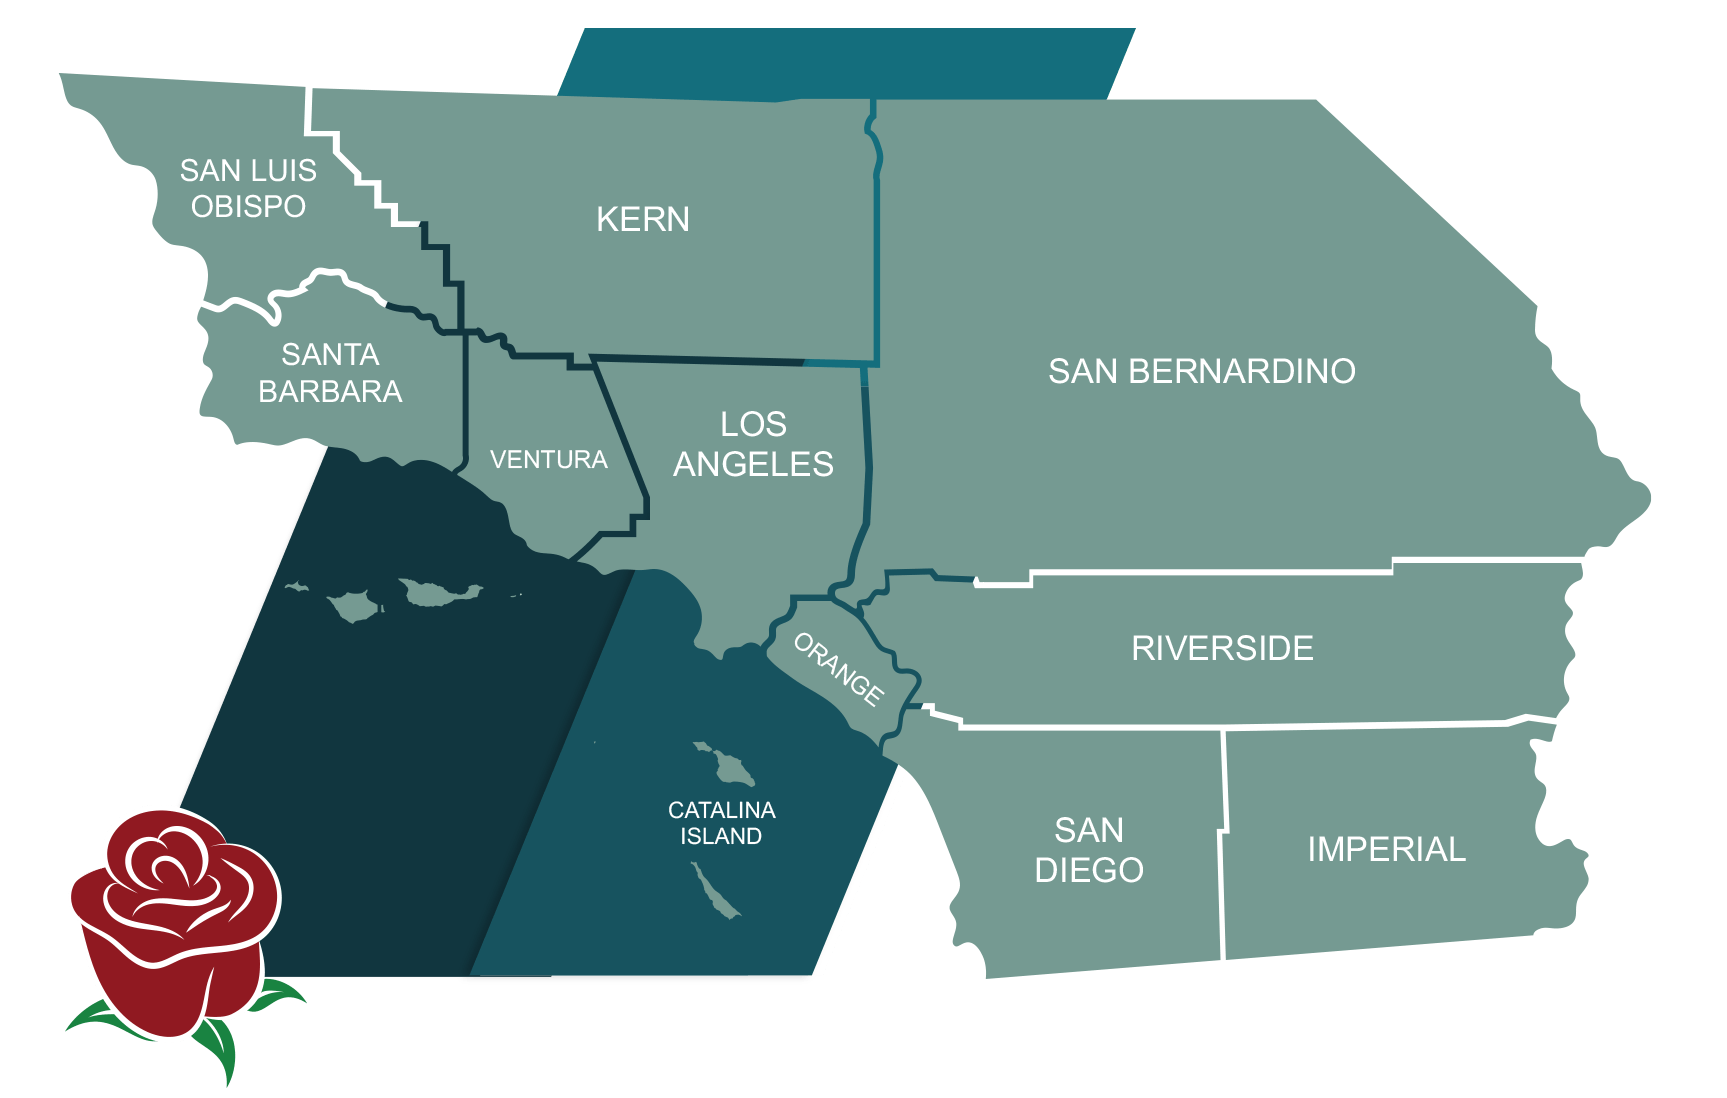
Local Service Hubs Serving Southern California
Is the Maintenance Plan Meet 2026 Green Goals?
Defining Primary Sustainability Performance Indicators